Your Local Mortgage Lender
Based in Louisville, Kentucky
Personalized Mortgage Experience
Jonathon Waunch offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
Review The Process
Work with our team to find your next home you would like to move into
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Chandler, Arizona.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
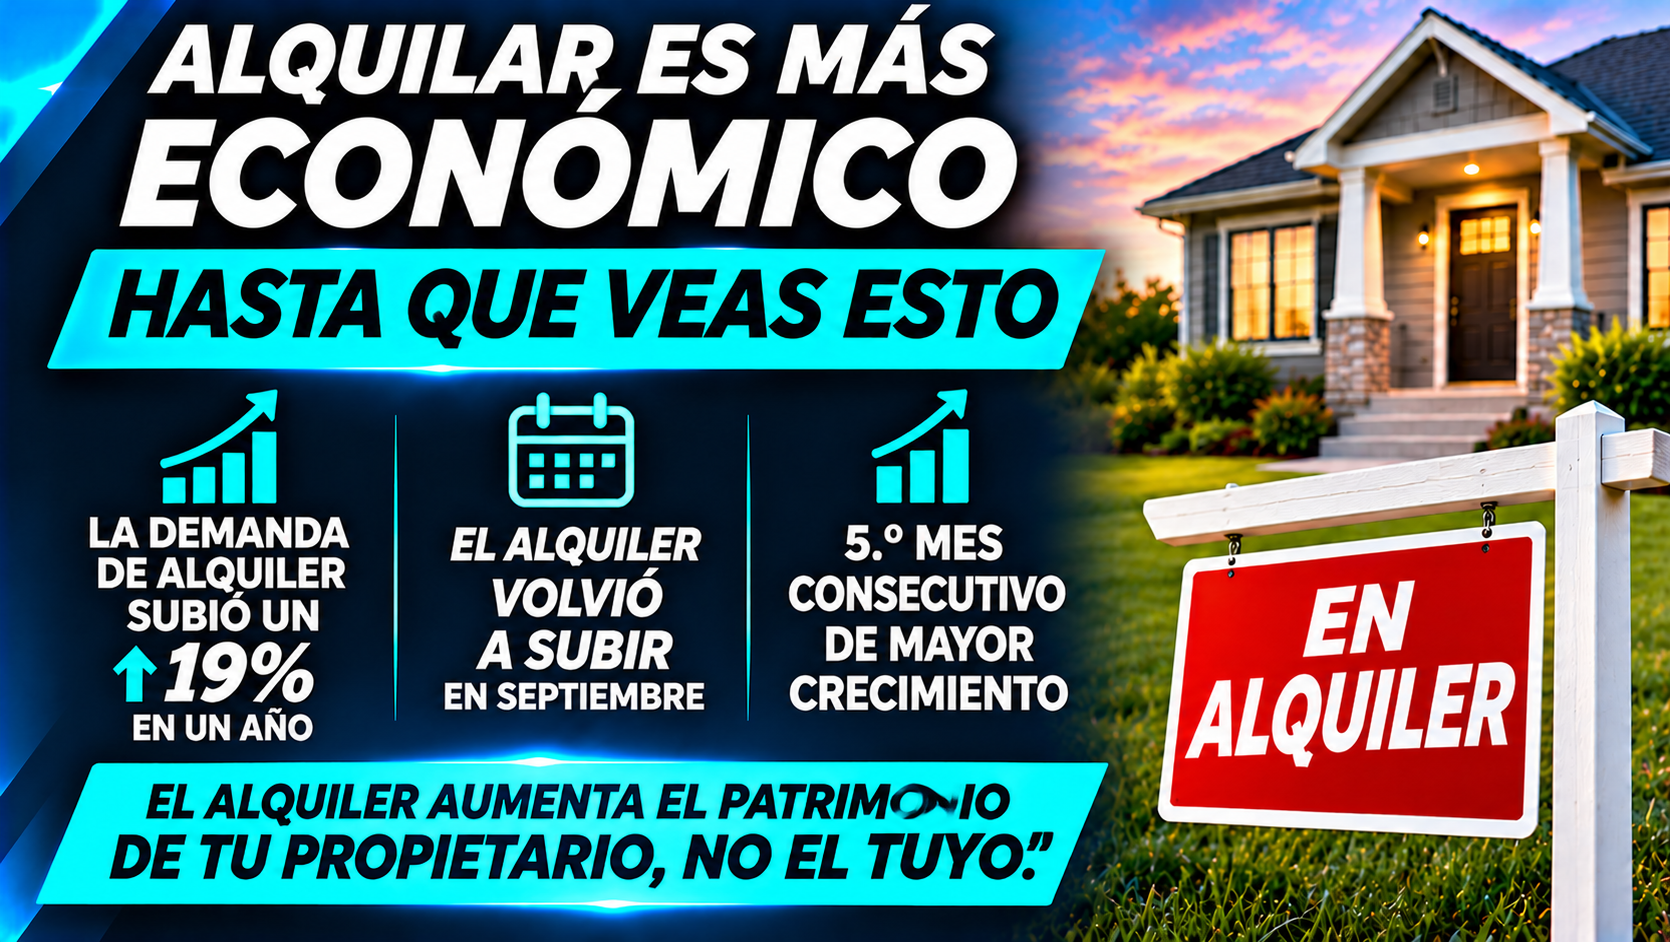
¿Alquilar es realmente más barato? Jonathon Waunch sobre los datos de demanda de Zillow y tus próximos 3 a 5 años
Alquilar parece más barato hasta que ves esto
Jonathon Waunch dice que alquilar puede parecer la opción más barata hasta que miras lo que está pasando en el mercado de alquileres. Un nuevo informe de Zillow encontró que la demanda de alquileres aumentó cerca de un 19% en un año, en gran parte porque muchos compradores están esperando fuera del mercado de compra. Cuando más hogares compiten por los mismos alquileres, la presión al alza sobre los precios es una consecuencia natural. Las cifras varían según el mercado, por lo que las condiciones locales importan.
El alquiler sigue subiendo
El informe también encontró que el alquiler típico volvió a subir en septiembre, el quinto mes consecutivo de crecimiento más rápido. Para los inquilinos, esto puede significar una factura más alta en la próxima renovación del contrato. Una hipoteca de tasa fija mantiene estable la parte de capital e intereses de tu pago, mientras que el alquiler puede subir con cada nuevo contrato, lo que dificulta planificar a futuro.
Alquilar puede ser lo correcto por una temporada
Jonathon es claro en que alquilar puede ser absolutamente la decisión correcta durante una etapa de la vida. Ofrece flexibilidad y funciona especialmente bien si estás ahorrando la diferencia a propósito. El dinero que se aparta deliberadamente para un pago inicial, reservas u otras metas puede convertir un periodo de alquiler en una estrategia en lugar de una demora.
¿El patrimonio de quién estás construyendo?
La contrapartida es que el alquiler construye el patrimonio de tu casero y no el tuyo. Los propietarios con hipoteca reducen su capital con el tiempo y pueden beneficiarse de la apreciación, aunque el valor de las viviendas nunca está garantizado que suba. Los propietarios también asumen costos que los inquilinos no tienen, como impuestos sobre la propiedad, seguro y mantenimiento, por lo que una comparación justa debe incluir el costo total de ser propietario y no solo el pago de la hipoteca.
Piensa en los próximos tres a cinco años
Jonathon sugiere que la pregunta no es alquilar o comprar para siempre. La pregunta es cómo se ven tus próximos tres a cinco años. Si esperas quedarte en un mismo lugar por varios años, ser propietario puede tener más sentido financiero. Si tus planes son inciertos o podrías mudarte pronto, alquilar puede ser mejor opción. Tu horizonte de tiempo, tus ahorros y tus metas deben guiar la decisión.
Compáralo lado a lado
Si estás evaluando tus opciones, Jonathon Waunch comparará tu alquiler actual con un pago real de vivienda propia, lado a lado, para que veas claramente la diferencia. Comunícate para hacer tus números.
Fuentes
Zillow.com
NAR.realtor
ConsumerFinancialProtectionBureau.gov
FreddieMac.com
HUD.gov

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Social Media Links
YouTube
