Su prestamista hipotecario local
Con sede en Louisville, Kentucky.
Experiencia hipotecaria personalizada
Jonathon Waunch le ofrece un servicio personalizado y opciones de préstamo que le encantarán. Buscamos entre múltiples prestamistas para encontrar la mejor tasa y el mejor producto para usted, ayudándole a conseguir la casa de sus sueños más rápido.
Con tasas de interés mayoristas y tecnología de vanguardia, hacemos que el proceso hipotecario sea sencillo. Confíe en los expertos que se dedican exclusivamente a las hipotecas. Apoye a su comunidad local y disfrute de un servicio al cliente excepcional.
Permítanos ayudarle a cumplir su sueño de tener una casa propia!
El proceso de préstamo hipotecario
Preaprobación de hipoteca
Obtén una preaprobación de uno de nuestros asesores de préstamos para saber cuánto puedes pagar.
Revisar el proceso
Trabaja con nuestro equipo para encontrar tu próximo hogar al que te gustaría mudarte.
Solicitud de préstamo
Complete su solicitud de préstamo hipotecario para iniciar el proceso de financiación.
No me creas a mí.
Programas hipotecarios
Disfrute de la mejor experiencia hipotecaria en Chandler, Arizona.
Opciones de préstamos hipotecarios
Nuestros asesores hipotecarios con experiencia le guiarán a través del programa de préstamo hipotecario que mejor se adapte a su situación particular.
Préstamos hipotecarios convencionales.
Préstamos hipotecarios de la FHA.
Préstamos hipotecarios del USDA.
Préstamos hipotecarios para veteranos.
Preguntas frecuentes
¿Con qué frecuencia puedo refinanciar mi hipoteca?
No hay límite en la cantidad de veces que puede refinanciar. Sin embargo, debe cumplir con los requisitos cada vez que solicite un préstamo y habrá costos asociados con el cierre del mismo en cada ocasión.
¿Puedo comprar una casa si no tengo dinero para el pago inicial?
¡Sí! Existen varios programas de bonos que ofrecen opciones de financiación con un pago inicial bajo o sin pago inicial.
¿Cómo puedo saber qué hipoteca es la adecuada para mí?
La clave para elegir la hipoteca adecuada reside en comprender la variedad de opciones y características disponibles, así como su presupuesto, circunstancias y objetivos. Nuestros asesores hipotecarios autorizados están aquí para ayudarle en este proceso. Cuanto más informado esté, más cómodo y seguro estará al elegir la mejor opción para usted y su familia.
¿Cuánto tiempo durará el proceso de solicitud del préstamo?
La Ley de Veracidad en los Préstamos (TILA, por sus siglas en inglés) prohíbe a los prestamistas formalizar un préstamo hasta que hayan transcurrido al menos siete (7) días hábiles desde la fecha de recepción de su solicitud. Un préstamo hipotecario típico tarda 30 días, ya que se requieren diversos servicios de terceros, como tasaciones, estudios de títulos y verificación de crédito, como parte del proceso hipotecario. Una vez que le explique a su asesor de préstamos los detalles de su caso particular, este podrá brindarle un cronograma más preciso.
¿Cumpliré los requisitos para obtener un préstamo hipotecario?
La única manera de averiguarlo es hablando con un asesor hipotecario cualificado. Nuestros asesores de préstamos han ayudado a numerosos clientes que no sabían si podían optar a la compra de una vivienda. Nos tomamos el tiempo necesario para comprender su situación financiera y sus objetivos a largo plazo, y luego le ofrecemos el programa de préstamo que mejor se adapta a sus necesidades. La aprobación de su préstamo también puede depender en gran medida del precio de la vivienda que desea financiar. Obtener una precalificación antes de comenzar la búsqueda de su casa puede darle una idea de lo que puede permitirse.
¿Por qué la gente refinancia sus hipotecas?
Los propietarios de viviendas suelen refinanciar sus hipotecas para ahorrar dinero, ya sea obteniendo una tasa de interés más baja o reduciendo el plazo del préstamo. La refinanciación también permite convertir un préstamo de tasa variable en uno de tasa fija o consolidar deudas.
¿Cuánto dinero tendré que pagar por adelantado para comprar una casa?
Esta pregunta no tiene una respuesta sencilla y universal. La cantidad exacta dependerá del precio de la vivienda que compre y del tipo de financiación hipotecaria que elija. Según el programa de préstamo, el pago inicial podría ser de hasta el 20 % del precio de la vivienda o tan solo del 3 %, mientras que algunos préstamos no requieren ningún pago inicial.
¿Puedo obtener una hipoteca después de declararme en bancarrota?
Aún podrías calificar para un préstamo hipotecario aunque te hayas declarado en bancarrota. La mejor manera de saber si calificas es hablar con un asesor de préstamos para analizar tus opciones. Asegúrate de llevar toda la documentación relacionada con tu bancarrota para que el asesor pueda encontrar el programa que mejor se adapte a tu situación.
¿Debo fijar mi tipo de interés ahora o esperar hasta que estemos más cerca del cierre de la operación?
Las tasas de interés fluctúan constantemente. Si una tasa es favorable, le conviene fijarla ahora. Si espera, corre el riesgo de que suban más adelante. Si le preocupa que las tasas bajen después de fijarla, comuníquese con su asesor de préstamos para analizar sus opciones. Algunos programas le permiten fijar la tasa por un período prolongado y optar por una tasa más baja si surge una mejor.
Últimas actualizaciones del blog
Most Economists Are Not Expecting a 2008 Repeat and Here Is What Buyers Should Focus on Instead
Most Economists Are Not Expecting a 2008 Repeat and Here Is What Buyers Should Focus on Instead
The Question That Comes Up Constantly and the Honest Answer
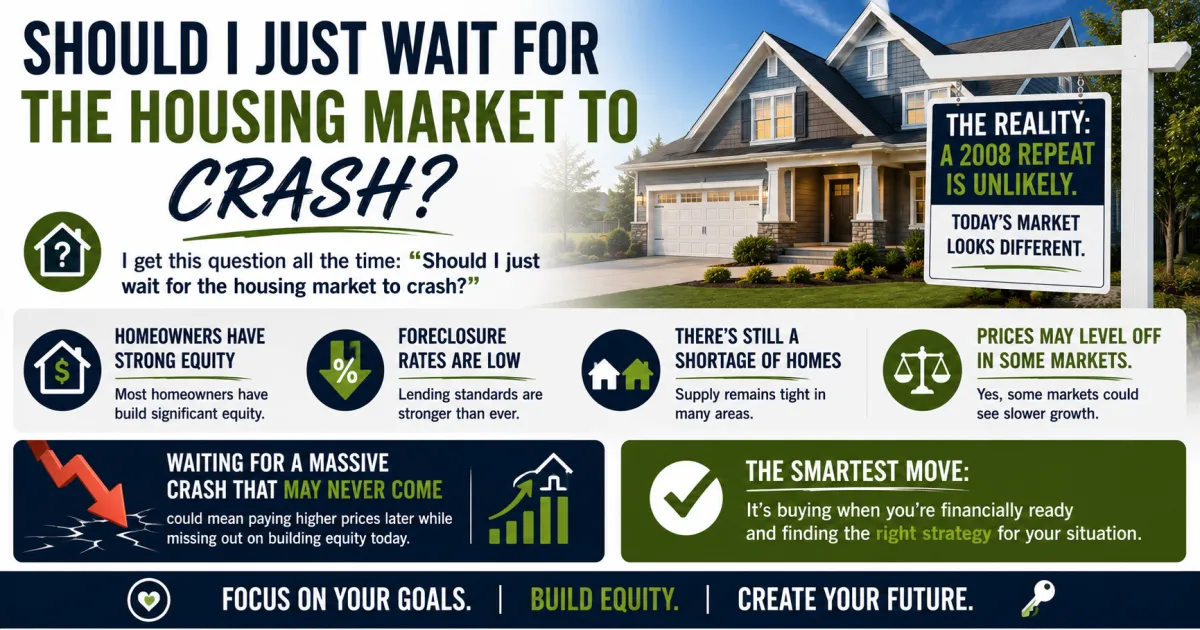
Should you just wait for the housing market to crash before buying? It is one of the most common questions Jonathan Waunch hears and it deserves a clear and honest answer grounded in what the current market actually shows rather than what the scary headlines suggest.
The short answer is that most economists are not expecting a repeat of 2008. But understanding why requires looking at what made 2008 what it was and why the current market does not share those characteristics.
Why 2008 Was Different and Why Today Is Not That
The 2008 housing crisis had specific and identifiable causes. Lending standards were dangerously loose and millions of buyers were placed into mortgages they could not realistically sustain. Home prices had been inflated by easy credit and speculative demand rather than genuine housing need. When those foundations gave way there was nothing structural underneath to support the market.
Today's market looks very different on every one of those dimensions. Homeowners have substantial equity built through years of appreciation and principal paydown. Foreclosure rates remain low. Lending standards have been significantly tighter since the qualified mortgage rules went into effect after 2008. And the fundamental supply problem driving prices in many markets is a genuine shortage of homes rather than speculative overbuilding.
What Could Actually Happen
As Jonathan Waunch explains prices could level off in some markets. In areas where appreciation has run significantly ahead of income growth some softening is possible and has already happened in isolated markets.
What is not being projected by most economists is the kind of broad severe sustained price decline that would make waiting for a crash the winning strategy. The conditions that produced 2008 are not present in the same way and the structural shortage of housing supply in many markets creates ongoing demand pressure that did not exist in the run-up to the last crisis.
The Real Cost of Waiting for Something That May Not Come
Waiting for a massive crash that may never arrive has a compounding cost that buyers tend to underestimate when they make the decision to wait.
Every month of waiting is a month of equity not building. Every month of appreciation that happens without ownership is wealth accumulating for someone else. And if rates improve during the waiting period demand returns with them. More buyers competing for the same limited inventory pushes prices back up and the negotiating leverage that exists in a quieter market disappears exactly when the buyers who have been waiting finally decide to act.
What the Smartest Move Actually Is
Trying to perfectly time the market is not a reliable strategy for most buyers. The smartest move is buying when you are financially ready and finding the right strategy for your specific situation given what the current market actually offers.
Jonathan Waunch works with buyers to evaluate their specific financial readiness and to build a purchasing strategy that makes sense for where the market is rather than where buyers hope it will be. Reach out to Jonathan Waunch to find out what the right move looks like for your situation right now.
Sources
NAR.realtor
MortgageNewsDaily.com
FederalReserve.gov
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Calculadora de hipotecas
Consulta el total de tus pagos hipotecarios con la herramienta que aparece a continuación.
| Year | Interest | Principal | Balance |
|---|
Enlaces a redes sociales
YouTube
a
